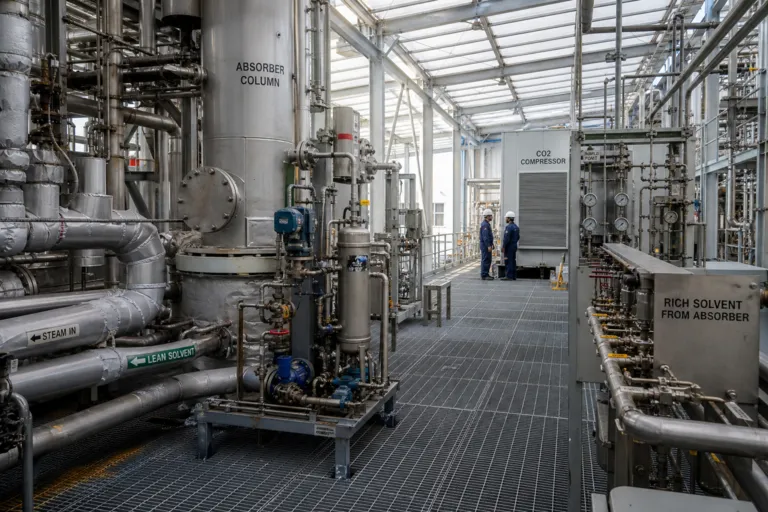
On Jurong Island, Singapore’s energy and chemicals base is being asked to decarbonise without losing its industrial edge. The island is home to over 100 global energy and chemicals companies, including Exxon-Mobil, BASF, Chevron Oronite, and Mitsui Chemicals. In parallel, more than 30 new specialty chemical projects have been set up in Singapore since 2021, with the majority on Jurong Island. This concentration matters for CCUS because hubs work best when multiple emitters can share capture, transport, and storage pathways. Singapore’s wider decarbonisation planning also points to carbon capture technology as one of the most effective mitigation measures for meeting its 2030 Nationally Determined Contribution targets.
Singapore’s official emissions context frames the urgency. Singapore’s greenhouse gas emissions measured about 58,590 kilotonnes of CO₂ or equivalent in 2022 and are expected to peak in 2028 before reducing to 60,000 kilotonnes in 2030. In its biennial transparency report submitted to the United Nations in November 2024, Singapore estimated that mitigation measures could reduce emissions by up to 12,000 kilotonnes by 2030. Within that, the expected contribution from CCS or CCUS is 20 percent of the total emissions reductions, removing up to 2,500 kilotonnes of CO₂ equivalent by 2030. That estimate puts CCUS into the category of “material impact” rather than a niche pilot.
Why Jurong Island Is a Natural CCUS Testbed
Jurong Island’s CCUS readiness is not only about emitters; it is also about innovation and execution in live industrial settings. JTC launched the Jurong Island Innovation Challenge to invite companies to co-develop and test solutions on-site. One pilot by Croda and Singapore start-up NanoSun focuses on wastewater treatment and aims to cut freshwater use and carbon emissions by 25 per cent. Separately, JTC and the Energy Market Authority’s Renewable Energy request for proposals enabled a collaboration between Advario, VFlowTech, and JTC to scale vanadium flow batteries using existing infrastructure on Jurong Island. These examples show how shared infrastructure and co-innovation can accelerate deployment timelines that matter for a Singapore carbon capture utilisation storage 2026 storyline.
Technology development is also being backed by funding and market participation. In Singapore’s carbon capture and climate tech market, investments in R&D reached SGD 500 million (approximately USD 370 million). The same market landscape lists a mix of regional and international players active in Singapore, including Keppel Corporation Limited, PacificLight Power, YTL PowerSeraya, Shell Eastern Petroleum, ExxonMobil Asia Pacific, Sembcorp Industries, Linde Singapore, TotalEnergies Gas & Power Asia, Mitsubishi Heavy Industries Asia Pacific, Siemens, Air Products Singapore, Climeworks AG, Carbon Clean Solutions Limited, and Aker Solutions ASA. That breadth supports an ecosystem approach, where capture equipment, industrial integration, and services can be developed in parallel rather than sequentially.
Singapore’s constraints also shape what “at the source” can realistically mean. The country lacks suitable underground sites to facilitate CCS, so it seeks to work with other countries for storage and to share best practices, including Indonesia, Malaysia, Japan, Brunei, and Australia. This makes regional partnerships a core part of any scaling plan from Jurong Island. Globally, CCUS momentum provides context: over 80 large-scale CCUS facilities are operational worldwide, collectively capturing approximately 40 million metric tons of CO₂ per year. Market outlooks also signal growth, even if they are not Singapore-specific: one forecast expects the global CCUS market to record a CAGR of 24.06% from 2025 to 2035, while a Rest of Asia Pacific CCUS market estimate values that region at USD 106.1 million in 2025 and projects USD 165.6 million by 2030 at a 9.3% CAGR. For Singapore, the implication is clear: the pathway depends on hub economics at home and storage pathways beyond its borders.
What role could CCUS play in Singapore’s 2030 emissions plan?
Why is Jurong Island central to Singapore’s CCUS push?
How does Singapore address the lack of local underground CO₂ storage?
What investment signals support a Singapore carbon capture, utilisation and storage outlook for 2026?